Tuesday, October 1, 2013

Money saving apps


1. Ibotta
      With this app you participate in tasks and earn money when you confirmed you've bought a participating product. You also get $10 just for signing up. (if you sign up from the link you and I get a bonus!)

2. Receipt Hog  (if you sign up from the link you and I get a bonus!)
      In this app you just take a picture of any grocery store receipt and then you'll receive points for how much you spent in each receipt. The points can be redeemed for $5 gift cards to Amazon.com or $5 into a paypal account. They're planning on expanding this to restaurants and gas purchases, but for right now it's just for groceries and other places that sell things that you would get at grocery stores (i.e. convenience stores or target/walmart)

3. Grocery IQ
     With this app you make a grocery list and the app lets you know of any coupons available for the items on your list. then you can either print them from a wifi enabled printer or you can receive them as an e-mail to print out. Note: Making a list before grocery shopping is a great way to stay in your budget and this app helps you do that. 

4. Cellfire 
    This is the best for the spontaneous shopper. you register your store savings cards and your cell phone number. Then, when you use your card or phone number relevant coupons are automatically redeemed. You can also download coupons to your phone or print out coupons the old fashioned way. 

5. Cartwheel 
     This is a T

arget specific app, but you can select offers that you would like to use and then the cashier just scans one coupon and the savings are applied to your order. Pretty darn awesome.


Edit: We also paid off another credit card! We're working on paying off my engagement/wedding ring now.


Frugality Gal

Monday, September 30, 2013

A Video

I was linked the following video and wanted to share it.


If you want to get my thoughts on the video, you can find them here at my blog that I use to discuss this type of information.

-Eric

Friday, September 27, 2013

Happy Friday

Well I was going to write something based off the video below, but I feel like I couldn't share it any better.

Since blogger is being finicky. here's the link.

Thursday, September 26, 2013

A huge key to success

    Both in my work as an advocate and when I listen to friends, family, and the Dave Ramsey show I see/hear a lot of people getting in their own way when it comes to success. They may have the solution handed to them on a silver platter, but they are saying that it's not good enough for them and immediately point out the faults in the plan. 

      This is not to say that the way that I'm choosing to do things is THE way and if you have problems with it that you're running yourself into the ground. But some parts of what I'm saying are pretty simple and universal. People tell me they have trouble having enough money to pay their bills each month, to which I clearly respond "well, have you made a budget?" and their like "Well it's hard because I have so little money" which it may be emotionally difficult but it's even more important because there's little to no cushion to make a mistake.

      Whatever your goal is, it's probably not easy. If running a marathon were easy, everyone would do it. If being debt free were easy, then the idea of bankruptcy would not exist. For each goal you have lookup what people are doing succeed at that goal and pick the path that works best for you. For example, I want to do a triathlon next fall. I know one weak spot is going to be running. So I'm running a little bit more than my average run in Nike+ every day so that my run is just a little bit longer every day. When I reach a 5k then I'll run a little bit faster pace than my average pace everyday. This way works for me because I tend to talk myself out of running for much longer so going out and saying "I'm going to run 3.2 miles every day" is not going to happen.
     You may have to work a crummy job, you may have to work 100 hours a week (not suggested), you may have to avoid eating out, or cancel your cable to meet your financial goals, but it's all worth it in the end when you can go from month to month without the stress of "am I going to be able to pay all my bills?" However, you have to get the reasons why you can't do something out of your head and try something new. What you've always done isn't working, so how do you know that something else won't work? 

Wednesday, September 25, 2013

Iowa Is the most debt free state!

Iowa is apparently the most debt free state in America. (see!) With only an average credit card balance of $2,904 per person. Maybe because I am knee-deep in Financial Peace University but that still seems like a lot. However, keep up the good work, Iowans!

Tuesday, September 24, 2013

Check your credit report

Hey blogosphere of mine,

 Thanks for the awesome support that I got from a lot of you today... er yesterday, overnights are messing with my concept of time. I had a quite upsetting moment when Eric and I had an unexpected bill on our credit report. However, we cleared it up and are working to stop future problems through a couple of different things.


Number one lesson from this.  Check your credit report. You can check from all three crediting bureaus once a year at this link here. Do it, and then mark on your calendar when to redo it. Even if you're not using debt or credit cards anymore it affects your renting ability, your insurance premiums (having too many accounts open raises your premium) and your security clearance if you're in the military or work some other government job. All of the things on your credit report stay on there for 7 years after the last activity, i.e. whenever you close the account.


Thanks guys for your help and support,
Bevin

Monday, September 23, 2013

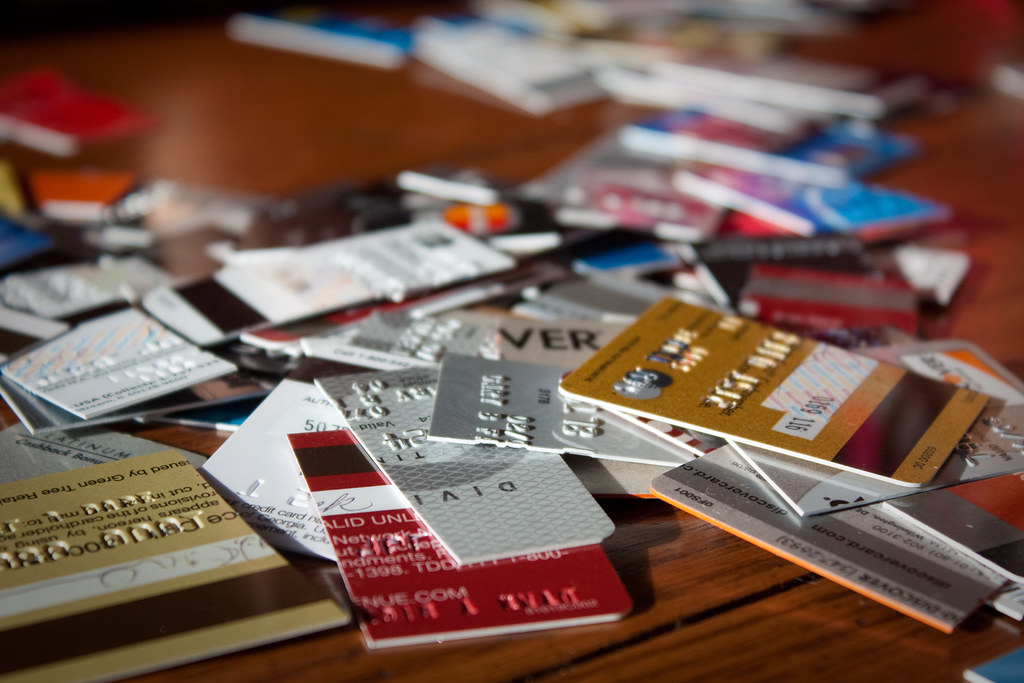
Cut up the cards!

Ladies and gentlemen... -drumroll- I cut up my cards!

Sorry to disappoint, but I didn't do anything funny or awesome, just cut them up and put them in the trash.

However, this is a very important and very hard step in the debt-free process. You have to:
1) have your emergency fund of $1000 so you don't need the credit card for emergencies.
2) Believe in your emergency fund
3) Remember that normal is broke. So you'll probably see comments on this post saying that I should keep one card open so that I can buy a house with a mortgage or I'll need a credit score to get a job, but really, you need a credit score if you want to keep using credit. The use of credit is your choice, but if you're not wanting to use credit anymore your FICO doesn't matter. Eric and I even intend to pay cash for a house, so, bye bye FICO.


If you want to have some fun cutting up cards, go for it! Have a get together where everyone cuts up their cards, run them over with your car, shoot them, blow them up, the sky's the limit. An important key to getting out of debt is to stop using debt as quickly as you can. I know everyone has their own personal situation and there's a HUGE paradigm shift you have to go through to be able to take that step to say you'll never use debt again.


Also, Vote for us so we can win a trip to hawaii by liking the pic at this link